Peter Tumbas
REALTOR® · Berkshire Hathaway HomeServices New England Properties
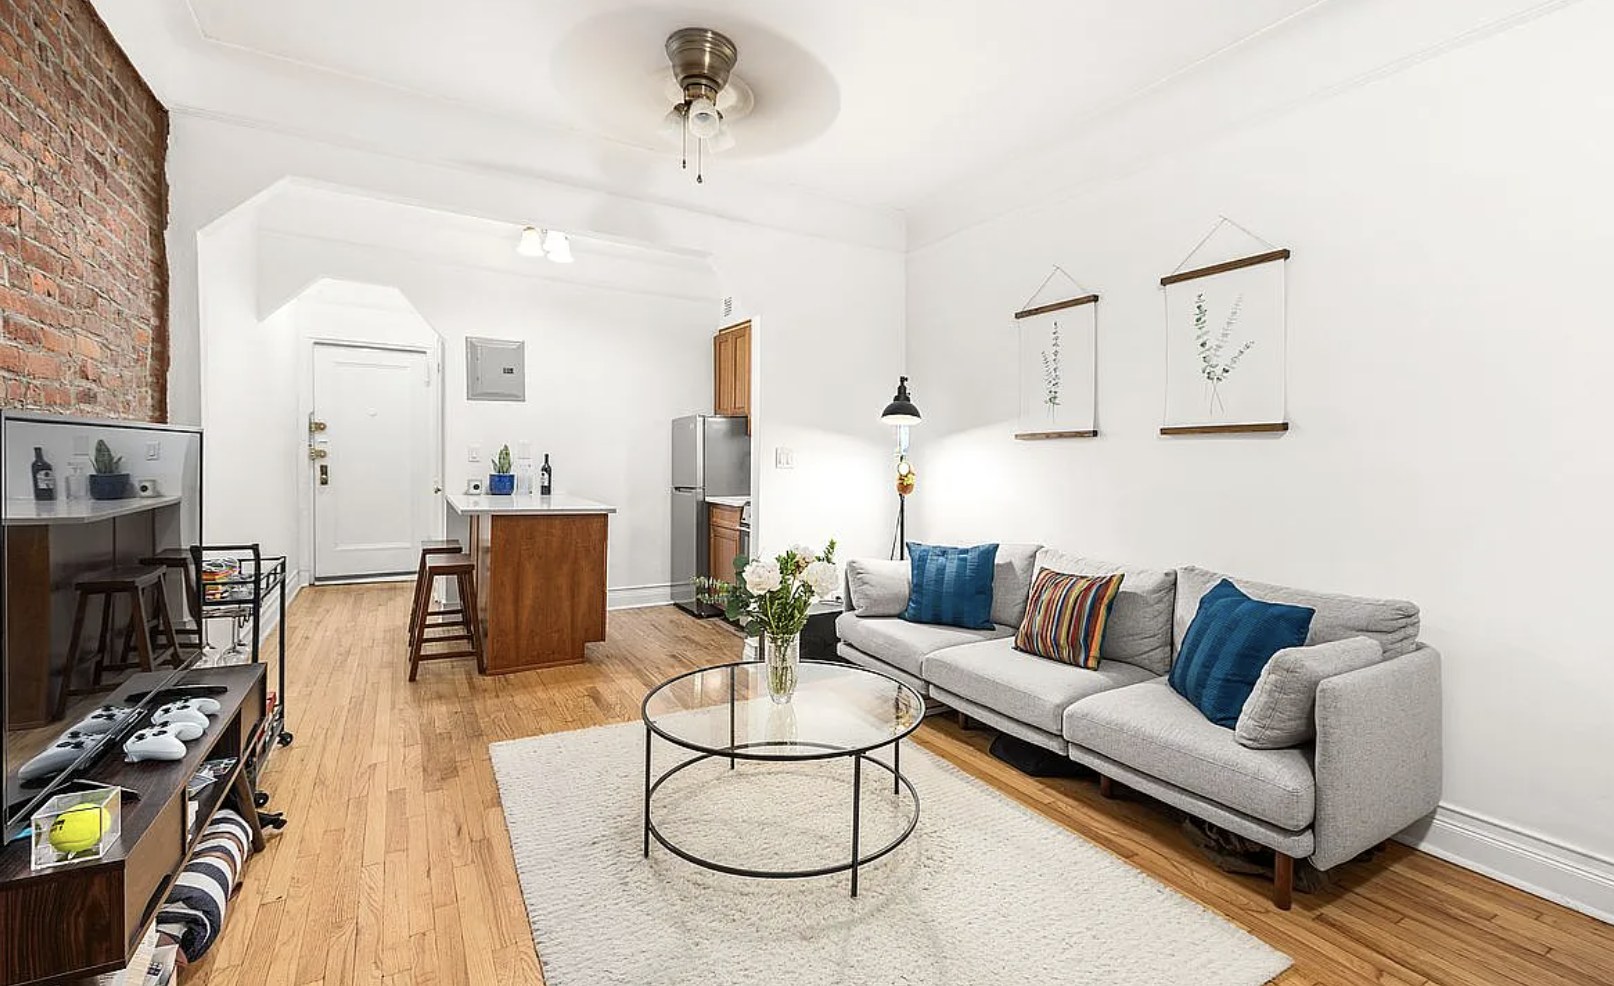
- A $4,500 rent costs $54,000 a year, about $540,000 over ten years, and sits below Manhattan's $4,900 median.
- On an $850,000 Upper East Side co-op with 3% yearly appreciation, owning beats renting in year 8 at 7.28% rates and year 5 to 6 at 6% to 6.5%.
A $4,500 rent costs $54,000 a year before you own a single thing. Rent keeps climbing across Manhattan and Brooklyn. The real question is not rent or mortgage. It is how long you plan to stay. This guide runs the math for an Upper East Side apartment with 2026 rents and rates, and shows where owning starts to win. Figures are as of October 5, 2026.
How much is rent in Manhattan and Brooklyn in 2026?
Manhattan's median rent was $4,900 in August 2026, up 6.5% from a year earlier, and Brooklyn's median was $4,000, up 1.3%, according to Brick Underground's summary of The Real Deal rental report by Jonathan Miller. Manhattan's vacancy rate fell to 1.51%, the lowest since 2019, and listings dropped 45.3% from August 2025. Fewer apartments for rent gives landlords the leverage.
A $4,500 rent sits below the Manhattan median, so the numbers in this guide are conservative. A renter on the Upper East Side paying the median or more pays higher costs than shown here.
What does ten years of renting cost?
At $4,500 a month you pay $54,000 a year and $540,000 over ten years if the rent never rises. Rents rise. With a 3% increase each year, ten years of renting costs $619,049. At the end you own nothing and start over at a higher rent.
What does ten years of owning cost?
Owning costs more per month at first. This model uses an $850,000 one-bedroom co-op on the Upper East Side with 20% down, a 30-year mortgage at 7.28% and $1,500 a month in maintenance. The 7.28% figure is the 30-year fixed average on October 1, 2026, per Freddie Mac. Principal and interest come to $4,653 a month. Add maintenance, which includes the building's property tax, and the monthly total is $6,153, or $1,653 more than the $4,500 rent.
The payoff comes from appreciation and from the principal you pay down. At 3% yearly appreciation, the apartment is worth about $1.14 million after ten years and your equity is about $555,000, which includes your $170,000 down payment. Manhattan's median sale price rose 5.9% in the third quarter from a year earlier, per Miller Samuel and The Real Deal, but one quarter does not set the next ten years.
To compare fairly, the model counts every cost of owning: mortgage interest, maintenance, 2.5% in buyer closing costs, 6.5% in selling costs, and a 4% return you give up on the cash you put in. It then subtracts the price gain. Rent is the only cost of renting.
Owning figures are net cost after interest, maintenance, closing and selling costs, and the return on the cash you tied up, minus price appreciation. Illustrative model, data as of October 5, 2026.
The chart shows what drives the result. At 3% appreciation, ten years of owning at 7.28% costs $551,650 net, less than $619,049 of rent with 3% increases. If prices go nowhere, owning costs $824,978 and renting wins by a wide margin.
When does owning get cheaper than renting?
With 3% yearly appreciation, owning beats renting in year 8 at today's 7.28% rate, year 6 at 6.50% and year 5 at 6.00%. That is why a break-even of five to seven years is a fair rule of thumb when rates sit near 6% to 6.5%. At 7.28%, plan on closer to eight years unless prices rise faster than 3%. At 4% appreciation, the break-even drops to year 4 or 5 at any of these rates.
| Yearly appreciation | 7.28% rate | 6.50% rate | 6.00% rate |
|---|---|---|---|
| 0% | Not within 12 years | Not within 12 years | Not within 12 years |
| 2% | Year 12 | Year 9 | Year 8 |
| 3% | Year 8 | Year 6 | Year 5 |
| 4% | Year 5 | Year 4 | Year 4 |
| 5% | Year 4 | Year 3 | Year 3 |
A larger down payment shortens the wait. At 25% down, 3% appreciation and 7.28%, owning beats renting in year 7. Rates fall when the market turns, and you can refinance a mortgage later but you cannot refinance the closing costs.
Is the real question how long you plan to stay?
Yes. Buying and selling an apartment costs a few percent each way, and those costs need years of appreciation and rent savings to pay back. If you will leave within two years, renting is cheaper in every scenario above. If you plan to stay past year seven, you are choosing between paying someone else's mortgage and paying your own.
How does the strategy change by property type on the Upper East Side?
- Co-ops. Lower purchase prices and closing costs than condos, but a board approves you and maintenance includes property tax. Budget for the co-op board package and read the building's financials.
- Condos. More financing flexibility and fewer restrictions, with higher closing costs and a separate tax bill. Compare the full monthly carry, not the price. See co-op or condo on the Upper East Side.
- Townhouses. You own the whole building and pay for its upkeep. The average townhouse price fell 18.6% in the third quarter, per Miller Samuel, so the break-even is harder to predict.
- Boundary blocks. Blocks near the edges of Lenox Hill, Carnegie Hill and Yorkville are priced differently from the core. Compare recent sales on the block, not the neighborhood average. Our Yorkville and Carnegie Hill comparison shows how much the two differ.
What should you do before you decide?
- Decide how long you will stay. Under four years favors renting. Past eight years favors owning if prices rise 3% a year or more.
- Get a current mortgage quote. A half point on the rate moves the break-even by about a year.
- Price the full cost. Closing costs run about 2% to 5%. See what it costs to buy on the Upper East Side in 2026.
- Check the market. Inventory is thin, so read the third-quarter 2026 Manhattan market update before you tour.
- Talk to a licensed New York agent. Peter introduces buyers to vetted agents who know each building and block.
Illustrative model, not a forecast, and not legal, tax or financial advice. Assumptions: $850,000 co-op, 20% down, 30-year fixed mortgage, $1,500 monthly maintenance rising 3% a year, rent rising 3% a year, 2.5% buyer closing costs, 6.5% selling costs, 4% return on cash invested. Your numbers will differ. Ask your lender and a New York attorney to run yours.
Frequently asked questions
How much is rent on the Upper East Side in 2026?
Manhattan's median rent was $4,900 in August 2026, up 6.5% from a year earlier, per The Real Deal rental report. Rents vary by building and apartment size, and listings fell 45.3% from a year earlier, which keeps asking prices high. A $4,500 rent is below the Manhattan median.
Is it cheaper to rent or buy in Manhattan in 2026?
Renting is cheaper for the first several years. On an $850,000 Upper East Side co-op with 20% down, owning costs $1,653 more per month than a $4,500 rent at today's 7.28% mortgage rate. With 3% yearly appreciation, owning becomes cheaper in about year 8. At 6% to 6.5% rates, the break-even falls to year 5 or 6. See also: What It Costs to Buy on the Upper East Side in 2026.
How long do you need to stay for buying to beat renting in New York?
Plan on five to eight years. The exact number depends on your mortgage rate, how fast prices rise and your down payment. Buying and selling costs run several percent each way, so a stay of two years or less favors renting in every scenario tested here.
Should I buy a co-op or a condo on the Upper East Side?
Co-ops cost less to buy and close, and maintenance includes property tax. Condos cost more up front and bill tax separately, but approval is usually simpler. Compare the full monthly cost and your timeline for each building, not only the price. See also: Co-op or Condo on the Upper East Side.
What do mortgage rates mean for rent versus buy in 2026?
The 30-year fixed rate averaged 7.28% on October 1, 2026, up from 6.34% a year earlier, per Freddie Mac. Each half point adds about a year to the break-even in this model. Get a current quote before you compare, and consider a larger down payment to shorten the wait. See also: Manhattan Sales Rise as Inventory Shrinks.
How do I get matched with an Upper East Side agent?
Submit a private inquiry with your budget, timeline and building type. Peter is a Connecticut-licensed REALTOR who introduces buyers to licensed New York agents. He does not represent buyers in New York. He matches you with an agent who works your neighborhood.
Sources
Ready to look on the Upper East Side?
Peter is a Connecticut-licensed REALTOR® who introduces buyers to licensed New York agents. Tell him your budget and building type and he will match you with the right one.
October 2026
Yorkville vs. Carnegie Hill: Which Upper East Side Neighborhood Fits?
Two very different ways to live on the Upper East Side, and the questions that decide between them.
Read →October 2026
Co-op or Condo on the Upper East Side: How to Choose
What you actually own, how approval and financing differ, and which buyers each structure suits.
Read →October 2026
What Goes Into a Co-op Board Package
The documents co-op boards ask for, how the review works, and how to prepare before you make an offer.
Read →October 3, 2026
How Much Does It Cost to Buy an Apartment on the Upper East Side in 2026? Price, Closing Costs, Taxes and Monthly Fees
Upper East Side prices, buyer closing costs, the mansion tax, monthly charges and the new pied-à-terre surcharge for co-op and condo purchases, with 2026 figures.
Read →October 4, 2026
Manhattan Sales Rise as Inventory Shrinks: What the Third Quarter 2026 Numbers Mean for Upper East Side Buyers
Manhattan closed sales rose 8% and listings fell 10.7% in the third quarter of 2026 while the median price held at a record $1.25 million. What it means for Upper East Side buyers.
Read →October 6, 2026
Will Upper East Side Prices Fall to Offset 7% Mortgage Rates? What Buyers and Sellers Should Do
Prices would have to fall 41% to offset a 7.28% mortgage rate against the 2021 low. Practical moves for Upper East Side buyers and sellers in the 2026 market.
Read →