Peter Tumbas
REALTOR® · Berkshire Hathaway HomeServices New England Properties
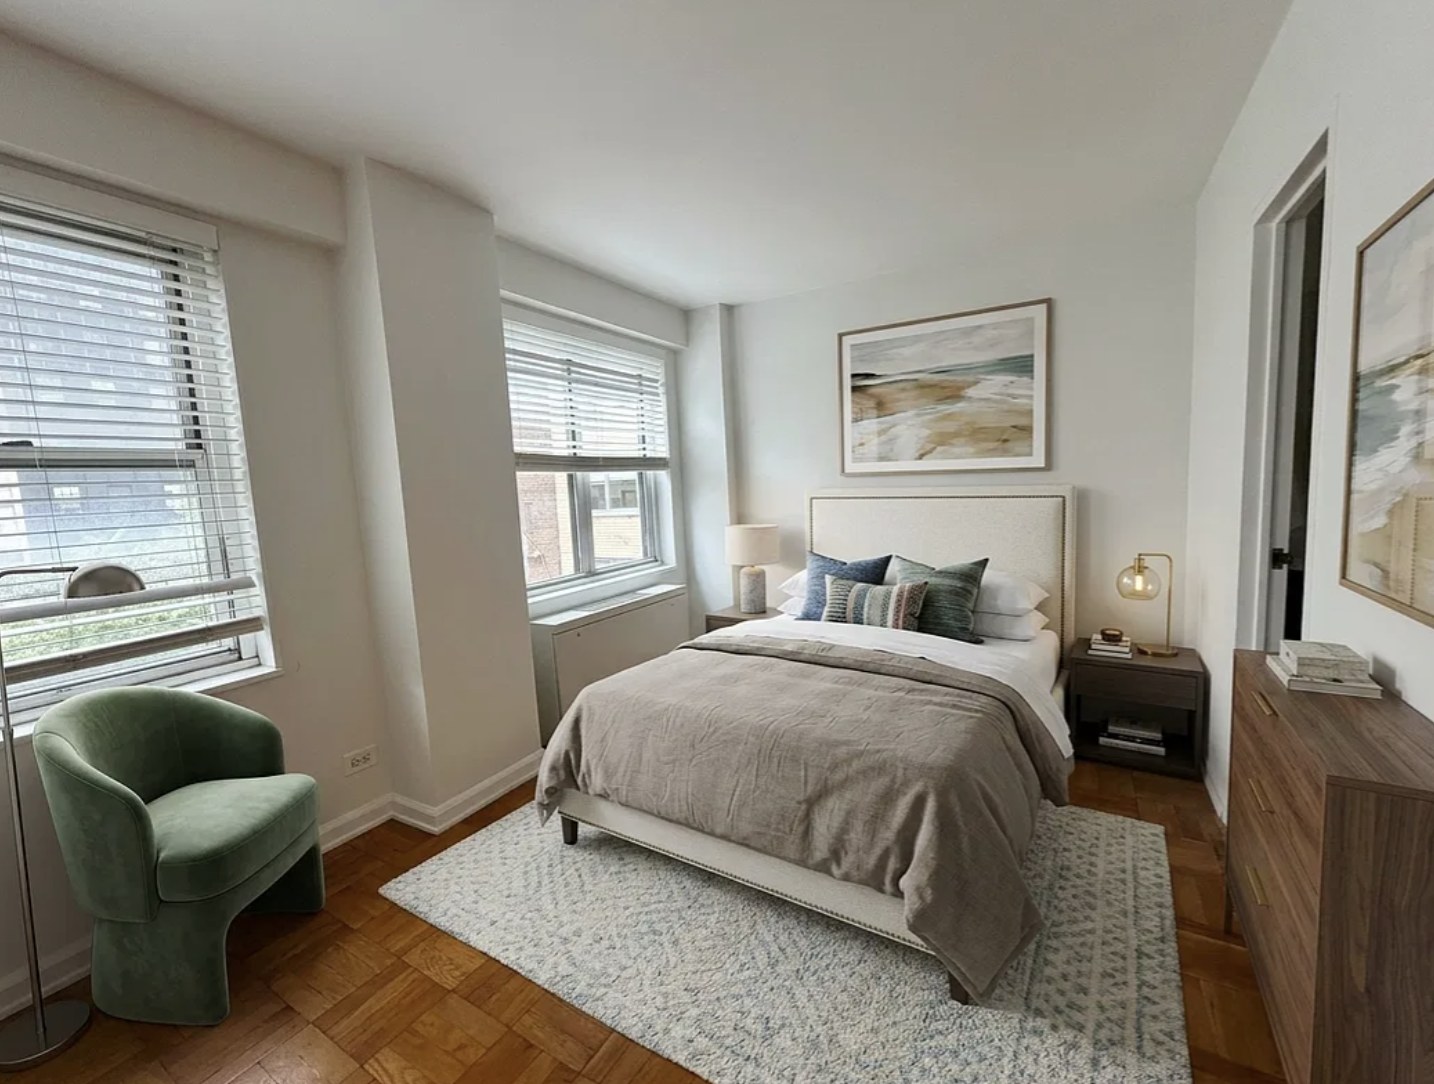
- Under $500,000, an Upper East Side buyer is looking at a studio or one-bedroom resale co-op, usually in an older building. Three October 2026 listings: $425,000 in Lenox Hill, $475,000 in Carnegie Hill and $419,900 in Yorkville.
- Maintenance on those three runs $1,262 to $1,536 a month, about 3.6% to 3.9% of the price each year. Plan on roughly $92,350 to $101,950 in cash for a $425,000 co-op at 20% down, and check board rules, any ground lease and the building's finances before you offer.
You can still buy on the Upper East Side for under $500,000, but it is a specific kind of purchase. In October 2026 that budget bought a studio or one-bedroom in a resale co-op, usually in a building from the mid-20th century or older. The prices look low next to the neighborhood's median, and the monthly costs and rules are where these apartments get decided. This guide walks through three current listings, one in each neighborhood, with the numbers a buyer should run before making an offer. Listing details are as of October 12, 2026 and can change.
Can you still buy on the Upper East Side for under $500,000?
Yes. The Upper East Side median sale price was $1,399,325 over the three months ending August 2026, and the median East Side resale co-op was $1.095 million in the second quarter, per our cost guide. An apartment under $500,000 sits well below both. In practice that means a studio or a one-bedroom, almost always a co-op, and often in a pre-war or mid-century building. Condos at this price are rare. Read co-op or condo for how the two differ.
What do three listings under $500,000 look like right now?
| Listing | Price | Maintenance | Building | On the market |
|---|---|---|---|---|
| Lenox Hill: 150 East 61st Street #7K, alcove studio, 1 bath | $425,000 | $1,280 | 1960, 16 stories, 131 units, full-time doorman | 3 days, listed October 9 |
| Carnegie Hill: 160 East 91st Street #4A, 1 bed, 1 bath | $475,000 | $1,536 | 1903, 8 stories, 125 units, part-time doorman | 19 days since relisting; first listed September 2025 at $499,000 |
| Yorkville: 415 East 80th Street #1B, 1 bed, 1 bath | $419,900 | $1,262 | 1959, 5 stories, 79 units, elevator, no doorman listed | 201 days; listed March 25 at $425,000, cut to $419,900 on September 8 |
All three are resale co-ops, and in all three the listing says taxes are included in maintenance. None of the listings gives square footage, so ask the agent for the floor plan and measured size before you compare price per square foot. StreetEasy's building details also list all three as allowing pied-à-terre use, subletting and guarantors. Treat that as a starting point and confirm each policy in writing, because boards can change them and exceptions apply.
What stands out in each one
- Lenox Hill, $425,000. It is the newest listing and has the most services: a full-time doorman, a gym, a bike room and parking. The listing says the building is on leased land, which makes it a ground lease co-op. Ask for the lease expiration date and how the rent is reset, because those terms can change your maintenance and affect financing.
- Carnegie Hill, $475,000. It has the highest maintenance of the three and the oldest building. The price fell from $499,000 to $475,000 between September 2025 and January 2026 before the listing was pulled and relisted at the same price in September 2026. That history gives you something to ask about, including how much room there is to negotiate.
- Yorkville, $419,900. It has the lowest maintenance and the lowest price, with an elevator and a live-in super but no doorman listed. It has been listed for 201 days after a small cut. A long listing is a reason to ask questions about the apartment and the building, and it does not prove a bargain.
What does each one cost per month?
The table assumes 20% down and a 30-year fixed loan at 7.28%, the average rate in our rates guide. It is an illustration. Your rate, down payment and the board's requirements will differ.
| Listing | Down payment | Mortgage (P&I) | Maintenance | Total | Maintenance as % of mortgage |
|---|---|---|---|---|---|
| Lenox Hill, $425,000 | $85,000 | $2,326 | $1,280 | $3,606 | 55% |
| Carnegie Hill, $475,000 | $95,000 | $2,600 | $1,536 | $4,136 | 59% |
| Yorkville, $419,900 | $83,980 | $2,298 | $1,262 | $3,560 | 55% |
Totals exclude electricity, your own insurance and any special assessment. Over a year, maintenance equals about 3.6% of the Lenox Hill price, 3.9% of the Carnegie Hill price and 3.6% of the Yorkville price. Lenders count maintenance in your debt-to-income ratio, so it limits how much you can borrow. Our guide to maintenance, common charges and hidden fees explains what the number covers and what it leaves out.
How much cash do you need?
Many co-op boards require 20% to 25% down, per our out-of-state buyer guide. On a $425,000 apartment, 20% is $85,000. Closing costs come on top. The mansion tax starts at $1 million, so it does not apply here. The remaining co-op fees in our cost guide, which are lender fees, both attorneys and the building's application and move-in charges, add about $7,350 to $16,950 on a $1,000,000 purchase. On a smaller loan they may run lower. That puts cash to close at roughly $92,350 to $101,950 for the Lenox Hill studio, before any post-closing cash reserves a board requires.
Are there first-time buyer programs that help?
Two programs are worth checking if you will live in the apartment and have not owned a home before:
- SONYMA Achieving the Dream. Allows as little as 3% down, with a 3% minimum cash contribution for co-ops, and 3% down payment assistance. Applicants must be first-time buyers (with exceptions for veterans and target areas), complete a homebuyer course and stay within income and price limits that vary by region, per New York State Homes and Community Renewal.
- NYC HomeFirst. Provides up to $100,000 toward a down payment or closing costs for first-time buyers, with a household income limit, a minimum 3% contribution from your own funds, a homebuyer course and a 10- or 15-year owner-occupancy period, per the NYC Housing Preservation and Development brochure. Check nyc.gov/homefirst for the current limits.
Both are for primary residences, so they do not suit a part-time apartment. Neither replaces board approval, and a board may limit how much you can finance. Ask a lender who works with co-ops about both before you offer.
What are the catches on a cheap co-op?
- Board approval. A board reviews your finances and often holds an interview. See the co-op board package guide.
- High maintenance relative to price. In these three listings it is about 3.6% to 3.9% of the price every year.
- Ground lease. Ask for the lease expiration date and renewal terms, and whether lenders finance in the building.
- Building finances. Ask for two years of financial statements, the reserve balance, the underlying mortgage and any planned or approved assessment.
- Small size. Studios and one-bedrooms can be tight. Get a floor plan and measure the space.
- Sublet and resale rules. Boards set limits that affect renting later, and some charge a flip tax when you sell.
Can you use one as a pied-à-terre?
Sometimes. These three buildings are listed as allowing part-time use, but many co-ops ban it. At this price, the city's new pied-à-terre surcharge is very unlikely to apply on current rules, because it targets condos and co-ops with a city value of $1 million or more. The income-tax residency rules and renting limits still matter. See our pied-à-terre checklist.
How do you start?
Tell us your budget, your preferred neighborhood and whether you will live in the apartment full time. We match you with a licensed New York agent who works Lenox Hill, Carnegie Hill or Yorkville and can check each building's rules, maintenance history and financials before you offer. Submit a private inquiry below.
General information only, not legal, tax or financial advice. Listing details come from public StreetEasy pages as of October 12, 2026, are not verified by us and can change or sell. The mortgage figures are an illustration with stated assumptions. Peter is licensed in Connecticut and does not represent buyers in New York. Confirm every number with your New York attorney and lender.
Frequently asked questions
Can you buy an apartment on the Upper East Side for under $500,000?
Yes, but expect a studio or one-bedroom in a resale co-op, usually in an older building. In October 2026 listings included a $425,000 studio in Lenox Hill, a $475,000 one-bedroom in Carnegie Hill and a $419,900 one-bedroom in Yorkville. The Upper East Side median sale price was $1,399,325 over the three months ending August 2026, so under $500,000 is a small-apartment budget. See also: What It Costs to Buy on the Upper East Side in 2026.
How much cash do you need to buy a $425,000 co-op?
At 20% down you need $85,000 for the down payment plus closing costs. Using the fee ranges in our cost guide, which exclude the mansion tax because it starts at $1 million, that is roughly $92,350 to $101,950. Some co-op boards also require cash reserves after closing, so ask the building for its limits. See also: What Goes Into a Co-op Board Package.
How high is maintenance on a cheap Upper East Side apartment?
In the three listings we reviewed, monthly maintenance was $1,262 to $1,536, which is about 3.6% to 3.9% of the asking price each year. Co-op maintenance includes the building's property tax. On a small apartment, maintenance can equal more than half of the mortgage payment. See also: Maintenance, Common Charges and Hidden Fees.
Are there first-time buyer programs for Upper East Side co-ops?
Two main ones. SONYMA's Achieving the Dream program allows as little as 3% down and 3% down payment assistance for first-time buyers, with income and price limits that vary by region. NYC's HomeFirst program offers up to $100,000 toward a down payment or closing costs for first-time buyers who live in the home, with income limits and a homebuyer course. Both are for primary residences, and the co-op board still must approve you.
Can I use a sub-$500,000 co-op as a pied-à-terre?
Possibly. StreetEasy listed all three of the example buildings as allowing pied-à-terre use and subletting, but many Upper East Side co-ops ban or restrict part-time owners. Confirm the policy in writing with the managing agent. At this price the city's new pied-à-terre surcharge is very unlikely to apply on current rules. See also: Pied-à-Terre Checklist.
What is a ground lease co-op?
In a ground lease co-op, the co-op corporation owns the building but leases the land underneath it. The listing for the Lenox Hill example says the building is on leased land. Ask for the lease expiration date, how the rent is set after renewal, how it affects maintenance, and whether your lender will finance in the building.
Sources
Ready to look on the Upper East Side?
Peter is a Connecticut-licensed REALTOR® who introduces buyers to licensed New York agents. Tell him your budget and building type and he will match you with the right one.
October 2026
Yorkville vs. Carnegie Hill: Which Upper East Side Neighborhood Fits?
Two very different ways to live on the Upper East Side, and the questions that decide between them.
Read →October 2026
Co-op or Condo on the Upper East Side: How to Choose
What you actually own, how approval and financing differ, and which buyers each structure suits.
Read →October 2026
What Goes Into a Co-op Board Package
The documents co-op boards ask for, how the review works, and how to prepare before you make an offer.
Read →October 3, 2026
How Much Does It Cost to Buy an Apartment on the Upper East Side in 2026? Price, Closing Costs, Taxes and Monthly Fees
Upper East Side prices, buyer closing costs, the mansion tax, monthly charges and the new pied-à-terre surcharge for co-op and condo purchases, with 2026 figures.
Read →October 4, 2026
Manhattan Sales Rise as Inventory Shrinks: What the Third Quarter 2026 Numbers Mean for Upper East Side Buyers
Manhattan closed sales rose 8% and listings fell 10.7% in the third quarter of 2026 while the median price held at a record $1.25 million. What it means for Upper East Side buyers.
Read →October 5, 2026
Rent vs. Buy on the Upper East Side in 2026: When Does Owning Beat Renting?
A $4,500 rent costs $54,000 a year. See what ten years of renting and owning cost on the Upper East Side and when owning breaks even at 2026 rents and mortgage rates.
Read →October 6, 2026
Will Upper East Side Prices Fall to Offset 7% Mortgage Rates? What Buyers and Sellers Should Do
Prices would have to fall 41% to offset a 7.28% mortgage rate against the 2021 low. Practical moves for Upper East Side buyers and sellers in the 2026 market.
Read →October 7, 2026
How to Buy an Apartment on the Upper East Side as an Out-of-State Buyer: A Step-by-Step Guide for 2026
The steps, deposit, timeline and costs to buy an Upper East Side apartment if you live outside New York, from preapproval and attorney to board approval and closing.
Read →October 8, 2026
Buying a Pied-à-Terre on the Upper East Side in 2026: A Checklist to Run Before You Make an Offer
Co-op rules, the new NYC pied-à-terre surcharge, New York tax residency, second-home financing and rental limits: eight checks to run before you buy a part-time apartment on the Upper East Side.
Read →October 9, 2026
Upper East Side Maintenance, Common Charges and Hidden Fees in 2026: What You Pay Every Month After You Buy
What co-op maintenance and condo common charges cover, what they leave out, typical Upper East Side ranges, and how to spot special assessments before you buy.
Read →