Peter Tumbas
REALTOR® · Berkshire Hathaway HomeServices New England Properties
- Many Upper East Side co-op boards interview buyers after reviewing the package. It is usually a 30-minute to one-hour meeting with a few board members, in person or by video, and a decision often follows within days. In New York City a board may reject for any reason or no reason, but not for an illegal one. One broker guide puts rejections at roughly 1 in 8 applications, mostly over finances, missing paperwork or inconsistent information.
- On a $525,000 one-bedroom at 20% down, a board will check $105,000 down, about $4,449 a month in housing cost on our assumptions (roughly $177,960 of income at a 30% ratio) and $53,388 to $106,776 in reserves at 12 to 24 months.
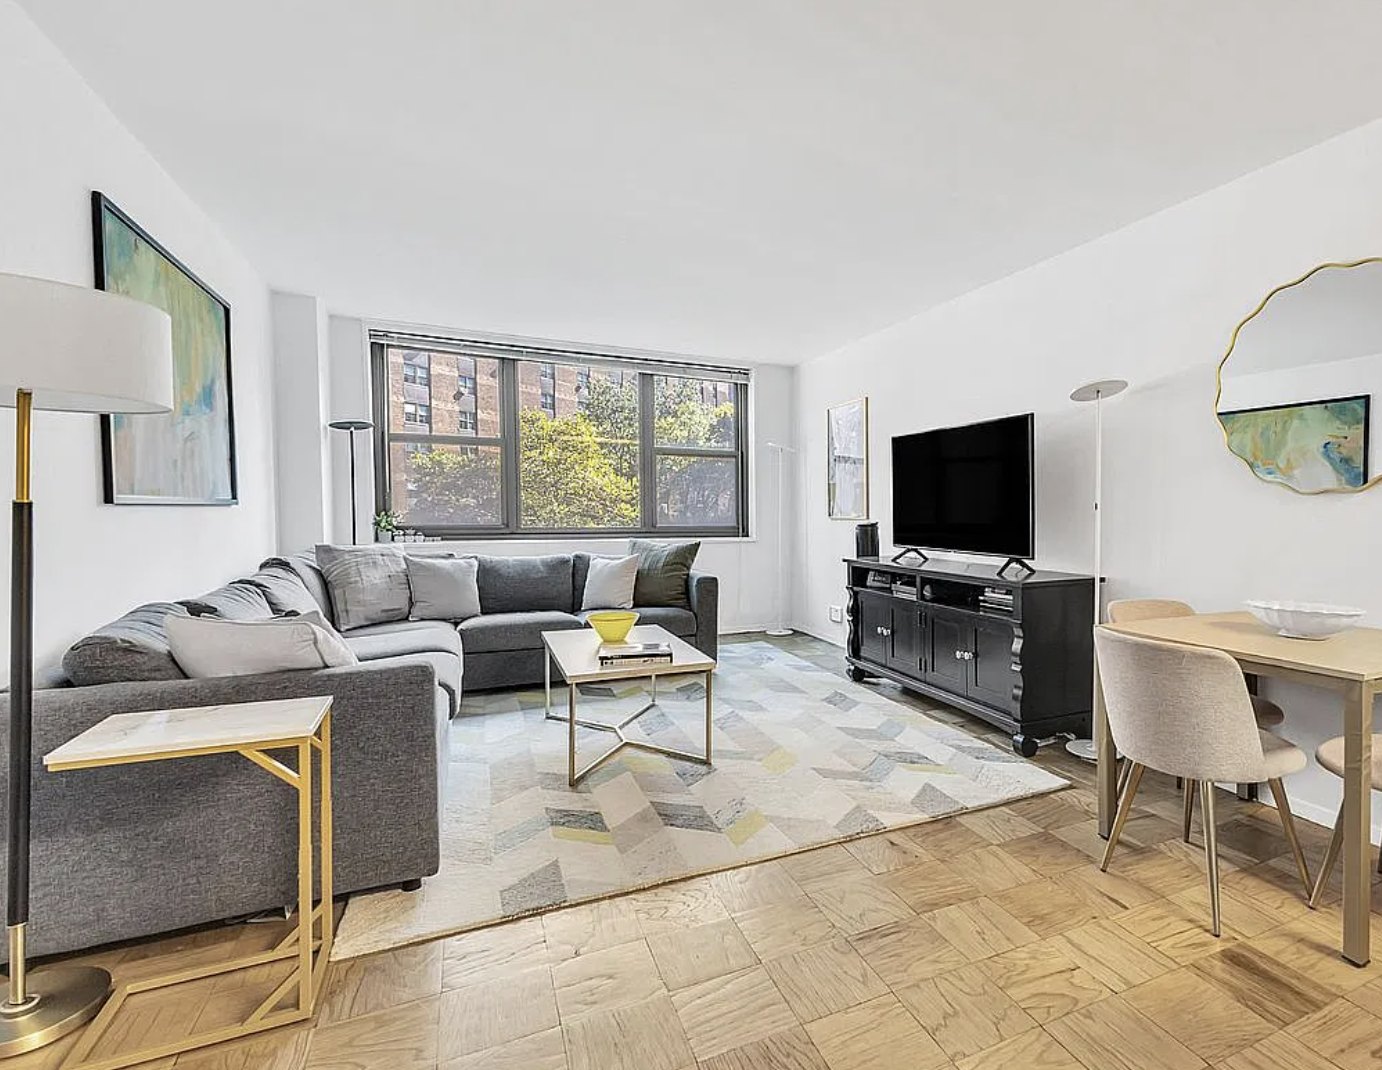
You have an accepted offer and a signed contract on a co-op. Now a group of your future neighbors decides whether you can buy. For many Upper East Side buyers that decision includes an interview. This guide explains what the interview is, what boards ask, how long approval takes, what a board can and cannot legally do, and the numbers to have ready. The worked example is a $525,000 Yorkville one-bedroom like the one pictured. We do not know that building's maintenance or board rules, so the figures use stated assumptions. Figures are as of October 19, 2026.
What is a co-op board interview?
After you submit your board package, the managing agent sends it to the board. Some boards then meet the buyer before they vote. One broker guide describes the interview as a meeting with a small group of board members, in person or virtual, that usually lasts 30 minutes to an hour and mixes formal and informal questions. Some boards skip the interview and decide on the paperwork alone, so ask your agent which this building does. Most condos do not run a financial board review, as our co-op or condo guide explains.
How long does board approval take?
Timing varies by building and by how complete your package is. This is the typical sequence in our out-of-state buyer guide.
| Stage | Typical timing | Who leads |
|---|---|---|
| Board application submitted | Within about 30 days of signing | You, your agent and attorney |
| Managing agent processing | 1 to 2 weeks | Building management |
| Interview notice | 1 week to 1 month after the board receives the package | The board |
| Decision after the interview | Usually 1 to 3 business days | The board |
| Closing after approval | About 10 to 14 days | Attorneys and lender |
Another broker guide says a board can take anywhere from a few days to a few weeks to decide. If you hear nothing for a week after you submit, it recommends a short follow-up email to the managing agent.
What questions do co-op boards ask?
Published guides describe a short list of core questions:
- Why this building? Boards want to hear why you chose it, and some like to hear you would join building events or committees.
- Your job. They confirm the employment details in your application.
- The house rules. They check that you understand the rules on pets, renovations and subletting.
- Your plans for the apartment. Be ready to explain any renovation and how you will use the home, as our board package guide notes.
- Your questions. Many boards end by asking whether you have any.
Behind the questions, boards weigh cash left after closing, debt-to-income, your credit profile, stable employment and any history of lawsuits, especially against landlords, according to a co-op attorney quoted in Habitat magazine. Boards may not ask about protected characteristics. A family-planning question is one example a broker guide gives of an improper one.
What numbers will the board check on a $525,000 one-bedroom?
Before you sit down, run the numbers the board will run. The table uses 20% down, a 30-year fixed rate of 7.28% (the rate in our rates guide), closing costs of 2% of the price, and maintenance assumed at 3.6% of the price a year, the same ratio as in our under-$500,000 guide.
| Item | Amount |
|---|---|
| Down payment (20%) | $105,000 |
| Mortgage | $420,000 |
| Principal and interest | $2,874 a month |
| Maintenance (assumed) | $1,575 a month |
| Monthly housing cost | $4,449 |
| Income needed if housing is 30% of income | $177,960 |
| Income needed if housing is 25% of income | $213,552 |
| Closing costs (2%) | $10,500 |
| Reserve at 12 months of mortgage plus maintenance | $53,388 |
| Reserve at 24 months of mortgage plus maintenance | $106,776 |
| Total cash with a 12-month reserve | $168,888 |
| Total cash with a 24-month reserve | $222,276 |
Down payment plus 2% closing costs plus the reserve. Illustration with assumed maintenance. Data as of October 19, 2026.
The income rows assume the board applies the ratio to housing cost alone. If it counts all monthly debts, you need more income or less debt. If the board counts maintenance alone for reserves, 12 to 24 months comes to $18,900 to $37,800. Our down payment guide explains which assets count toward reserves. Whatever you say in the room should match the figures in your package. A broker guide lists inconsistent information among the common causes of rejection.
Can a co-op board reject you for no reason?
In New York City, yes. Habitat magazine reported on April 27, 2026 that a board may reject an application "for any reason or no reason" and does not have to explain its decision. Westchester County has a law requiring boards to give a reason, but New York City does not. A bill from the Public Advocate that would require a reason within five days has not advanced in the City Council, according to the same report.
Boards still cannot reject a buyer for an illegal reason under federal, state or city fair housing law. The protected classes include race, religion, national origin, age, disability, sexual orientation and gender identity. A lawyer quoted in the article notes that discrimination is hard to prove when the board gives no reason and there is no other evidence. If you suspect a rejection was discriminatory, speak to a New York attorney promptly.
How often do boards say no, and why?
One broker guide says roughly 1 in 8 co-op board applications gets rejected. That is a broker's estimate, not an official statistic. The same guide says most rejections trace to financial concerns, incomplete paperwork or inconsistent information, and that most are not personal. That makes the package and the building's standards the part you control. Ask your agent early how strict this board is, and read our guide to a co-op's financial statements so you ask informed questions in return.
How do you prepare?
- Build the package early. Recent pay stubs, two years of tax returns, bank statements, an employment letter and a personal financial statement. Keep a copy in a binder.
- Explain anything unusual. Business income or a recent job change belongs in a short cover letter, as our board package guide advises.
- Learn the house rules. Know the building's policies on pets, renovations and subletting before you arrive.
- Practice out loud. Rehearse your answers, dress professionally and arrive 10 to 15 minutes early. For a video interview, test your technology and choose a private, well-lit room.
- Bring questions. Ask about reserves, any planned assessment or façade work, and the sublet and pet policies. These are our suggestions, and the building's financial statements show where to probe.
- Use your team. Your agent and attorney can learn how this board behaves, and Habitat reports that sellers can hire a broker familiar with the building to vet purchasers. A buyer's agent with the same knowledge can tell you what to expect.
What if you live out of state?
Ask the managing agent early whether the board interviews by video. One broker guide says interviews may be in person or virtual. If the board wants you in the room, plan the trip around the interview notice, which can arrive anywhere from a week to a month after the board gets your package. Our out-of-state guide shows where the interview sits in the full timeline.
How do you start?
Tell us your budget, your preferred neighborhood and how much cash you have set aside. We match you with a licensed New York agent who works Yorkville, Carnegie Hill or Lenox Hill and knows which boards interview and how strict they are, plus a lender who works with co-ops. Submit a private inquiry below.
General information only, not legal, tax or financial advice. Each board sets its own rules and processes, and the figures in broker guides are not official standards. The worked example is an illustration with stated assumptions, not a quote or a statement about the Yorkville listing in the photo. Peter is licensed in Connecticut and does not represent buyers in New York. Confirm every step with your New York attorney and lender.
Frequently asked questions
What happens at a co-op board interview?
A small group of board members meets the buyer, in person or by video, for a mix of formal and informal questions, usually for 30 minutes to an hour. Boards typically ask why you want the building, confirm the employment details in your application, check that you understand the house rules and invite your questions. Not every board interviews buyers. See also: What Goes Into a Co-op Board Package.
How long does co-op board approval take?
Timing varies by building. A typical sequence is about 30 days after contract to submit the package, 1 to 2 weeks of managing agent processing, an interview notice 1 week to 1 month after the board receives the package, and a decision usually 1 to 3 business days after the interview. One broker guide says boards can take anywhere from a few days to a few weeks to decide. See also: Out-of-State Buyer Guide.
What questions do co-op boards ask?
Expect questions about why you want the building, your employment, whether you understand rules on pets, renovations and subletting, how you will use the apartment and any planned renovation, and whether you have questions for the board. Boards weigh cash left after closing, debt-to-income, credit, stable employment and lawsuit history. They may not ask about protected characteristics such as family planning.
Can a co-op board reject you for no reason?
In New York City, yes. A board may reject an application for any reason or no reason and does not have to explain. It may not reject a buyer for an illegal reason under federal, state or city fair housing law, such as race, religion, national origin, age, disability, sexual orientation or gender identity. If you think a rejection was discriminatory, speak to a New York attorney.
How often do co-op boards reject buyers?
One broker guide says roughly 1 in 8 co-op board applications gets rejected. That is a broker's estimate, not an official statistic. The same guide says most rejections come from financial concerns, incomplete paperwork or inconsistent information. See also: How to Read a Co-op's Financial Statements.
What numbers will a board check on a $525,000 one-bedroom?
Four: your down payment ($105,000 at 20%), your monthly housing cost against your income (about $4,449 a month on our assumptions, which needs roughly $177,960 of income at a 30% ratio), your cash after closing (12 to 24 months of reserves, about $53,388 to $106,776), and your credit and employment history. Each building sets its own limits. See also: How Much Down Do You Need for an Upper East Side Co-op?.
Can I do the board interview remotely if I live out of state?
Often, but it depends on the board. One broker guide says interviews may be in person or virtual. Ask the managing agent early which this board uses, so you can plan any trip. See also: Out-of-State Buyer Guide.
Sources
- Habitat magazine: Co-op Boards Can Reject Buyers for Any Reason or No Reason (April 27, 2026)
- Milton Coste: NYC co-op board interview guide (April 2026)
- Milton Coste: NYC co-op post-closing liquidity requirements
- Skybriz: Down payment requirements for co-ops in NYC (2026)
- Freddie Mac Primary Mortgage Market Survey, 7.28% 30-year average on October 1, 2026
Buying a co-op in Yorkville?
Peter is a Connecticut-licensed REALTOR® who introduces buyers to licensed New York agents. Tell him your budget and building type and he will match you with the right one.
October 2026
Yorkville vs. Carnegie Hill: Which Upper East Side Neighborhood Fits?
Two very different ways to live on the Upper East Side, and the questions that decide between them.
Read →October 2026
Co-op or Condo on the Upper East Side: How to Choose
What you actually own, how approval and financing differ, and which buyers each structure suits.
Read →October 2026
What Goes Into a Co-op Board Package
The documents co-op boards ask for, how the review works, and how to prepare before you make an offer.
Read →October 3, 2026
How Much Does It Cost to Buy an Apartment on the Upper East Side in 2026? Price, Closing Costs, Taxes and Monthly Fees
Upper East Side prices, buyer closing costs, the mansion tax, monthly charges and the new pied-à-terre surcharge for co-op and condo purchases, with 2026 figures.
Read →October 4, 2026
Manhattan Sales Rise as Inventory Shrinks: What the Third Quarter 2026 Numbers Mean for Upper East Side Buyers
Manhattan closed sales rose 8% and listings fell 10.7% in the third quarter of 2026 while the median price held at a record $1.25 million. What it means for Upper East Side buyers.
Read →October 5, 2026
Rent vs. Buy on the Upper East Side in 2026: When Does Owning Beat Renting?
A $4,500 rent costs $54,000 a year. See what ten years of renting and owning cost on the Upper East Side and when owning breaks even at 2026 rents and mortgage rates.
Read →October 6, 2026
Will Upper East Side Prices Fall to Offset 7% Mortgage Rates? What Buyers and Sellers Should Do
Prices would have to fall 41% to offset a 7.28% mortgage rate against the 2021 low. Practical moves for Upper East Side buyers and sellers in the 2026 market.
Read →October 7, 2026
How to Buy an Apartment on the Upper East Side as an Out-of-State Buyer: A Step-by-Step Guide for 2026
The steps, deposit, timeline and costs to buy an Upper East Side apartment if you live outside New York, from preapproval and attorney to board approval and closing.
Read →October 8, 2026
Buying a Pied-à-Terre on the Upper East Side in 2026: A Checklist to Run Before You Make an Offer
Co-op rules, the new NYC pied-à-terre surcharge, New York tax residency, second-home financing and rental limits: eight checks to run before you buy a part-time apartment on the Upper East Side.
Read →October 9, 2026
Upper East Side Maintenance, Common Charges and Hidden Fees in 2026: What You Pay Every Month After You Buy
What co-op maintenance and condo common charges cover, what they leave out, typical Upper East Side ranges, and how to spot special assessments before you buy.
Read →October 13, 2026
How to Read a Co-op's Financial Statements Before You Offer: The 10 Numbers Upper East Side Buyers Should Check
Reserves, underlying mortgage, arrears, sponsor-owned units, assessments and audit notes: what each number means, what to look for and the red flags in a co-op building's finances.
Read →October 14, 2026
Manhattan Rents Are Up 7.7% While Rental Listings Shrink: Why Some Upper East Side Renters Should Run the Numbers on Buying
Manhattan median rent is $4,900 and rental listings have fallen 15 months in a row. What the September 2026 rental report shows, what it does not, and when buying is worth a serious look.
Read →October 15, 2026
How Much Down Do You Need for an Upper East Side Co-op? Down Payment, Debt-to-Income and Cash Reserve Rules Explained
Most Upper East Side co-op boards look at three numbers: your down payment, your debt-to-income ratio and the cash you keep after closing. Typical ranges, what counts, and a worked example on a $329,000 one-bedroom.
Read →October 16, 2026
How Much Will You Net Selling an Upper East Side Co-op? Transfer Taxes, Flip Tax, Commission and Closing Costs Explained
What a $1,595,000 Upper East Side sale leaves in your pocket: transfer taxes, flip tax, commission, attorney and building fees, a worked net proceeds table and the tax on your gain.
Read →October 18, 2026
Why Upper East Side Apartments Are Priced at $999,000: How the $1 Million Mansion Tax Line Changes Your Offer
A $999,000 asking price sits $1,000 under the $1 million mansion tax line. What a $1,000,000 bid really costs, the cash needed on a $999,000 two-bedroom, and how buyers and sellers should offer and price.
Read →October 12, 2026
How to Buy an Apartment Under $500,000 on the Upper East Side in 2026: What You Get, What to Check and the Catches
Three real Upper East Side listings under $500,000, what they cost each month, how much cash you need, first-time buyer loan programs and the co-op catches to check before you offer.
Read →October 20, 2026
Local Law 11 Façade Inspections and Special Assessments: What Upper East Side Co-op Buyers Should Check Before They Offer in 2026
What NYC's façade inspection law means for a co-op buyer: Safe, SWARMP and Unsafe reports, sidewalk shed rules, how a special assessment could hit your share, and what to ask before you offer.
Read →October 21, 2026
Can You Renovate an Upper East Side Co-op? Alteration Agreements, Board Approval, Costs and Timelines in 2026
What an alteration agreement is, what a board needs before you renovate, the fees and timeline before work starts, what renovation costs per square foot, and what to check before you offer.
Read →October 22, 2026
What Happens at a Co-op Closing in Manhattan? Documents, Cash Due, Timeline and a Closing-Day Checklist for 2026
The documents, cash due, timeline and closing-day checklist for a Manhattan co-op purchase, with a worked example on a $675,000 Yorkville one-bedroom.
Read →October 23, 2026
Buying a $1.375 Million Upper East Side Co-op: Is It a Jumbo Loan? Down Payment, Mansion Tax and Cash Needed in 2026
Whether a $1.375 million co-op loan is a jumbo, plus the down payment, $13,750 mansion tax, cash to close and monthly cost, with a worked example on a Yorkville two-bedroom.
Read →October 25, 2026
Buying a Newly Renovated Studio on the Upper East Side: What to Check on a $319,000 Yorkville Co-op in 2026
What a "newly renovated" studio co-op does and does not tell you, the documents to request, monthly cost, cash to close and sublet rules, with a worked example on a $319,000 Yorkville studio.
Read →October 28, 2026
Buying a Ground-Lease Co-op in Lenox Hill: Lease Expiration, Rent Resets, Financing and What to Ask Before You Offer in 2026
How a ground-lease co-op works, why the rent reset and lease expiration matter, a real Lenox Hill listing, and cash to close at $1.195 million, with the questions to ask before you offer.
Read →October 29, 2026
How to Make an Offer on an Upper East Side Apartment: Bidding, the Contract, the 10% Deposit and the New 45-Day Co-op Board Clock in 2026
What an offer includes, how negotiation and the contract work, the 10% deposit, contingencies and the new 45-day co-op board clock, with a worked example on a $549,000 Yorkville one-bedroom.
Read →