Peter Tumbas
REALTOR® · Berkshire Hathaway HomeServices New England Properties
- Manhattan median rent was $4,900 in September 2026, up 7.7% in a year, while rental listings fell 22.7% for the 15th straight monthly decline, per The Real Deal. Tight rentals and rising rents make owning more attractive to some renters.
- Owning costs more per month at the start ($6,153 vs. $4,900 in our $850,000 co-op example). If rent keeps rising and you stay five to eight years, buying is worth a serious look. The report does not measure buying, and rents may flatten.
Rent in Manhattan keeps climbing, and there are fewer apartments to rent. That does not mean everyone should buy, but it does mean a renter paying more each year should compare the cost of owning. This guide covers what The Real Deal's September 2026 rental report shows, what it does not show and when buying deserves a serious look. Figures are as of October 14, 2026.
What does the September 2026 rental report show?
The Real Deal's September rental report for Manhattan found a tight market with steady prices:
| Measure | September 2026 | Change |
|---|---|---|
| Median rent | $4,900 | Up 7.7% from September 2025; flat from August |
| Luxury median rent | $16,591 | Up 18.1% from a year earlier |
| Rental listings | Down 22.7% from a year earlier | 15th straight monthly decline |
| Lease signings | Down 15.3% from a year earlier | Fewer deals as well as fewer listings |
| New leases with bidding wars | 16% | Down from 22.1% in September 2025 |
| Days on market | 20 | Down from 39 |
| Vacancy rate | About 1.5% | Per Corcoran; lowest September supply since 2019 |
The median first topped $5,000 in July, a record, then eased back to $4,900. A 7.7% yearly increase on $4,900 is about $350 more a month, or roughly $4,200 a year, than a renter paid a year ago.
Why do tight rentals make owning more attractive?
Three effects stack up for a renter who plans to stay in the neighborhood:
- Fewer choices. With listings down for 15 months, a renter has less room to negotiate and fewer apartments to pick from.
- Rent resets higher. A lease renews at the market, so the payment can rise every year. A fixed-rate mortgage payment of principal and interest does not change for 30 years.
- Rent builds no equity. A mortgage payment pays down your loan. Rent pays the landlord's costs and profit.
Buying has its own costs: a down payment, closing costs, monthly maintenance or common charges and a board review for most co-ops. The sections below put numbers on both sides.
What does owning cost compared with $4,900 rent?
We use the same model as our rent vs. buy guide: an $850,000 Upper East Side co-op, 20% down ($170,000), a 30-year mortgage at 7.28% (the Freddie Mac average on October 1, 2026) and $1,500 a month in maintenance. Principal and interest are $4,653 a month, so the monthly total is $6,153. That is $1,253 more than the $4,900 median rent. Owning costs more each month at the start. The case for buying rests on what happens if rent keeps rising and you stay long enough for equity and price growth to catch up.
| Yearly rent increase | Monthly rent in year 5 | Rent paid over 5 years | Years until rent reaches $6,153 |
|---|---|---|---|
| 0% (flat) | $4,900 | $294,000 | Never |
| 3% | $5,680 | $312,177 | 7.7 years |
| 5% | $6,254 | $324,907 | 4.7 years |
| 7.7% (last year's pace) | $7,100 | $342,899 | 3.1 years |
$6,153 is the owner's monthly total today. The owner's maintenance also rises over time, so the owner's total would be about $6,392 in year 5 if maintenance grows 3% a year, while principal and interest stay fixed. This table compares monthly cash flow only. It leaves out closing costs, selling costs, the return on your down payment and the equity and price gain you keep as an owner, which our rent vs. buy guide includes. Rents have no guaranteed path, and 7.7% is one year's change.
What would a smaller purchase look like?
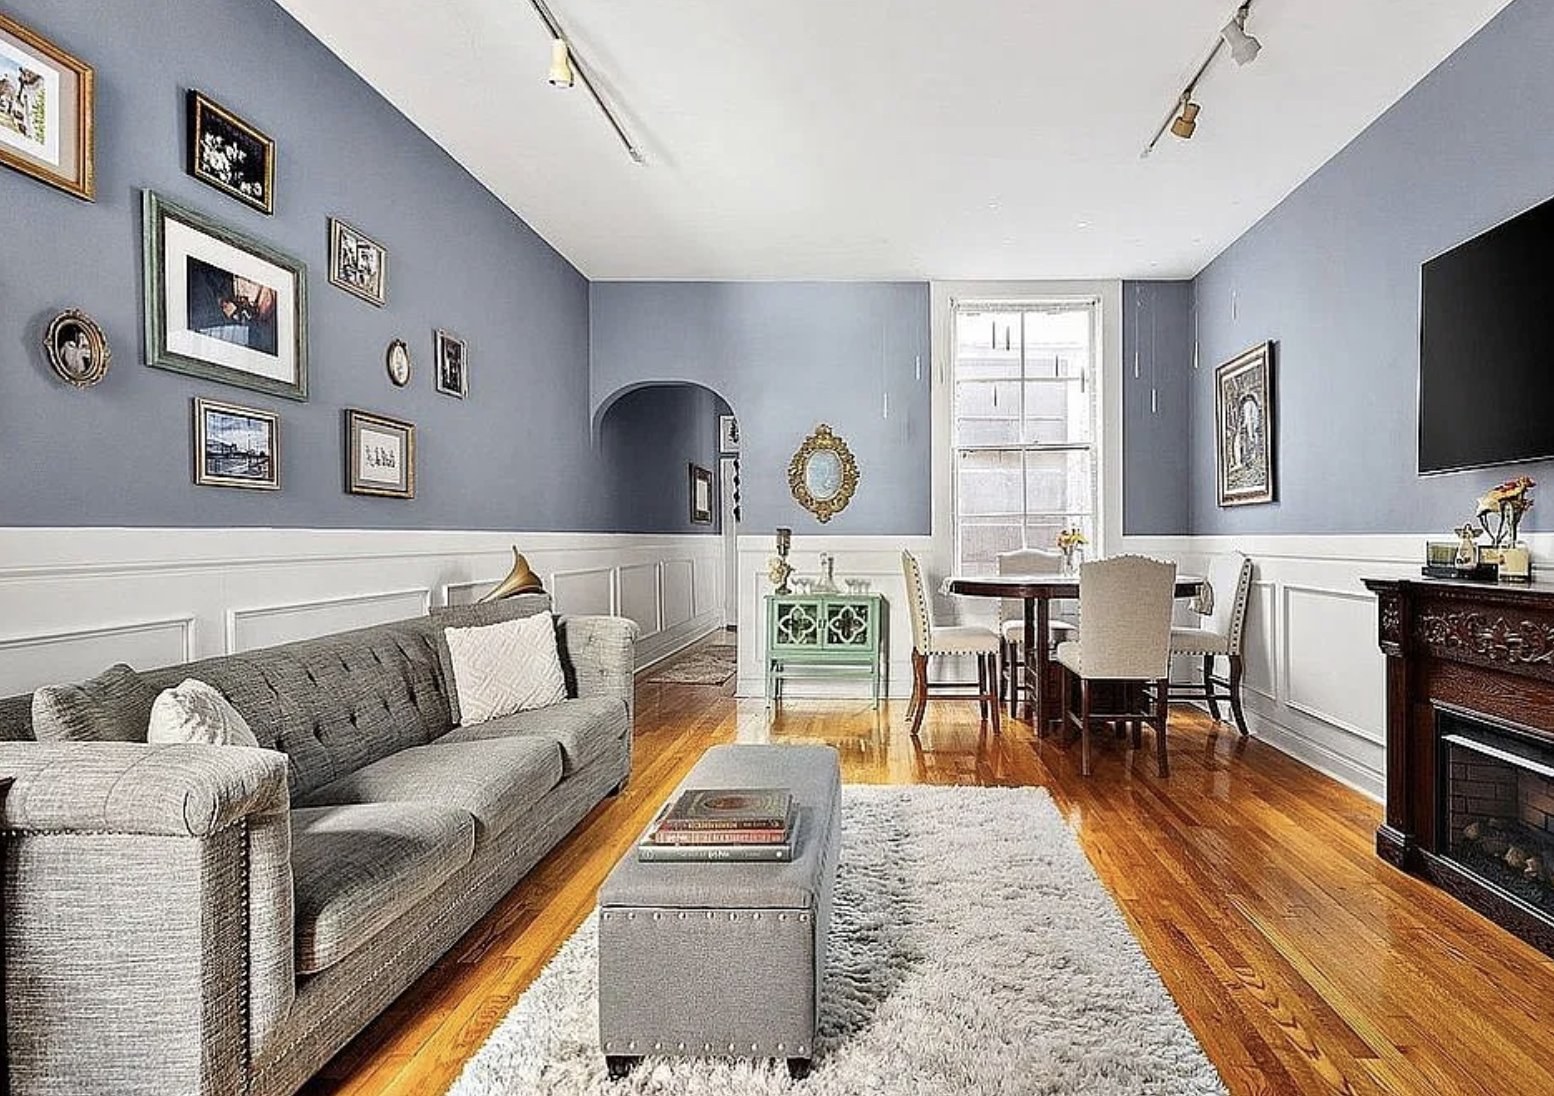
The apartment in the photo is a Carnegie Hill one-bedroom asking $479,000. With 20% down ($95,800) and a 7.28% mortgage on the remaining $383,200, principal and interest are about $2,622 a month. We do not know that building's maintenance, so as an illustration we use 3.9% of the price a year, the ratio of the Carnegie Hill example in our under-$500,000 guide. That adds about $1,557 a month, for roughly $4,179 in total. Compare that with a $4,900 median rent, and keep in mind that the median covers all Manhattan apartments, not one-bedrooms near Carnegie Hill. Closing costs and cash reserves come on top of the down payment, as in our cost to buy guide.
What does the report not tell you?
- It does not measure buying. It covers rentals. It does not show how many renters buy. Sales data is the place to check, such as the 8% rise in Manhattan closed sales in the third quarter in our Q3 market update.
- Rents may flatten. The median was unchanged from August to September, and the share of new leases with bidding wars fell to 16% from 22.1%.
- The median is not your apartment. It covers every Manhattan rental. Your own rent and building matter more.
Who should consider buying, and who should keep renting?
Worth a serious look:
- You plan to stay in the same area for at least five to eight years.
- You have the down payment, closing costs and a cash cushion without draining savings.
- Your income is stable and the monthly total fits your budget after the board's financial tests.
- Your rent has risen at renewals and you expect it to keep rising.
Renting may still fit:
- You may move within a few years, since closing and selling costs take years of price growth to recover.
- You would need to stretch to reach 20% down, or your cash would run thin after closing.
- You want to wait for a lower mortgage rate. You can refinance later if rates fall, but nobody can promise they will.
How do you test whether buying works for you?
- Write down your current rent and its last few increases.
- Get a mortgage preapproval from a lender that finances Manhattan co-ops and condos.
- Price your monthly total: principal and interest, maintenance or common charges, and insurance.
- Decide how long you will stay and compare that with the break-even years in our rent vs. buy guide.
- For co-ops, review the building's finances. Our guide to reading co-op financial statements lists the ten numbers to check.
How do you start?
Tell us your budget, neighborhood and how long you plan to stay. We match you with a licensed New York agent who can walk you through listings in Carnegie Hill, Lenox Hill and Yorkville and the monthly costs of each. Submit a private inquiry below.
General information only, not legal, tax or financial advice. Rent and mortgage figures are from published reports as of October 14, 2026 and change monthly. The tables are illustrations using stated assumptions, not forecasts. Corcoran's vacancy figure is as reported alongside the rental data. Peter is licensed in Connecticut and does not represent buyers in New York.
Frequently asked questions
Are Manhattan rents still rising?
Yes on a yearly basis, but not month to month. The Real Deal's September 2026 rental report put Manhattan's median rent at $4,900, up 7.7% from September 2025 and unchanged from August. Listings were down 22.7% from a year earlier, the 15th straight monthly decline.
Does it make sense to buy if rents keep rising?
It is worth running the numbers. A fixed-rate mortgage payment of principal and interest stays the same while rent can rise at every renewal, and you build equity as you pay down the loan. Owning still costs more per month at first and only pays off if you stay long enough. Our rent vs. buy guide shows the break-even years at different rates and price growth. See also: Rent vs. Buy on the Upper East Side in 2026.
How long do I need to stay for buying to beat renting?
In our model of an $850,000 co-op with 20% down, a 7.28% rate and a $4,500 rent, owning beats renting in year 8 at 3% yearly price growth, year 5 at 4% and year 4 at 5%. If prices do not rise, owning does not catch up within 12 years. Plan on five to eight years.
What if rents stop rising or fall?
Then the case for buying weakens, and renting keeps its flexibility. The report shows mixed signals: median rent was flat from August to September, and the share of new leases with bidding wars fell to 16% from 22.1% a year earlier. Decide on your own time horizon and budget, and not on a rent forecast.
Does a lower rental inventory mean more people will buy?
The report does not say that. It measures rentals only. Tight rentals can push some renters toward ownership, but others stay put, move to other boroughs or leave the city. Sales data, such as Manhattan closed sales, is the place to look for buying activity. See also: Third quarter 2026 Manhattan numbers.
Sources
- The Real Deal: Manhattan rents stayed put at $4,900 in September (October 8, 2026)
- The Real Deal: Manhattan rents crack $5k median in July, a new record (August 13, 2026)
- The Real Deal: Manhattan inventory slips as deals rise in Q3 (October 2, 2026)
- Freddie Mac Primary Mortgage Market Survey, 7.28% 30-year average on October 1, 2026
Ready to look on the Upper East Side?
Peter is a Connecticut-licensed REALTOR® who introduces buyers to licensed New York agents. Tell him your budget and building type and he will match you with the right one.
October 2026
Yorkville vs. Carnegie Hill: Which Upper East Side Neighborhood Fits?
Two very different ways to live on the Upper East Side, and the questions that decide between them.
Read →October 2026
Co-op or Condo on the Upper East Side: How to Choose
What you actually own, how approval and financing differ, and which buyers each structure suits.
Read →October 2026
What Goes Into a Co-op Board Package
The documents co-op boards ask for, how the review works, and how to prepare before you make an offer.
Read →October 3, 2026
How Much Does It Cost to Buy an Apartment on the Upper East Side in 2026? Price, Closing Costs, Taxes and Monthly Fees
Upper East Side prices, buyer closing costs, the mansion tax, monthly charges and the new pied-à-terre surcharge for co-op and condo purchases, with 2026 figures.
Read →October 4, 2026
Manhattan Sales Rise as Inventory Shrinks: What the Third Quarter 2026 Numbers Mean for Upper East Side Buyers
Manhattan closed sales rose 8% and listings fell 10.7% in the third quarter of 2026 while the median price held at a record $1.25 million. What it means for Upper East Side buyers.
Read →October 5, 2026
Rent vs. Buy on the Upper East Side in 2026: When Does Owning Beat Renting?
A $4,500 rent costs $54,000 a year. See what ten years of renting and owning cost on the Upper East Side and when owning breaks even at 2026 rents and mortgage rates.
Read →October 6, 2026
Will Upper East Side Prices Fall to Offset 7% Mortgage Rates? What Buyers and Sellers Should Do
Prices would have to fall 41% to offset a 7.28% mortgage rate against the 2021 low. Practical moves for Upper East Side buyers and sellers in the 2026 market.
Read →October 7, 2026
How to Buy an Apartment on the Upper East Side as an Out-of-State Buyer: A Step-by-Step Guide for 2026
The steps, deposit, timeline and costs to buy an Upper East Side apartment if you live outside New York, from preapproval and attorney to board approval and closing.
Read →October 8, 2026
Buying a Pied-à-Terre on the Upper East Side in 2026: A Checklist to Run Before You Make an Offer
Co-op rules, the new NYC pied-à-terre surcharge, New York tax residency, second-home financing and rental limits: eight checks to run before you buy a part-time apartment on the Upper East Side.
Read →October 9, 2026
Upper East Side Maintenance, Common Charges and Hidden Fees in 2026: What You Pay Every Month After You Buy
What co-op maintenance and condo common charges cover, what they leave out, typical Upper East Side ranges, and how to spot special assessments before you buy.
Read →October 12, 2026
How to Buy an Apartment Under $500,000 on the Upper East Side in 2026: What You Get, What to Check and the Catches
Three real Upper East Side listings under $500,000, what they cost each month, how much cash you need, first-time buyer loan programs and the co-op catches to check before you offer.
Read →October 13, 2026
How to Read a Co-op's Financial Statements Before You Offer: The 10 Numbers Upper East Side Buyers Should Check
Reserves, underlying mortgage, arrears, sponsor-owned units, assessments and audit notes: what each number means, what to look for and the red flags in a co-op building's finances.
Read →October 15, 2026
How Much Down Do You Need for an Upper East Side Co-op? Down Payment, Debt-to-Income and Cash Reserve Rules Explained
Most Upper East Side co-op boards look at three numbers: your down payment, your debt-to-income ratio and the cash you keep after closing. Typical ranges, what counts, and a worked example on a $329,000 one-bedroom.
Read →October 16, 2026
How Much Will You Net Selling an Upper East Side Co-op? Transfer Taxes, Flip Tax, Commission and Closing Costs Explained
What a $1,595,000 Upper East Side sale leaves in your pocket: transfer taxes, flip tax, commission, attorney and building fees, a worked net proceeds table and the tax on your gain.
Read →October 18, 2026
Why Upper East Side Apartments Are Priced at $999,000: How the $1 Million Mansion Tax Line Changes Your Offer
A $999,000 asking price sits $1,000 under the $1 million mansion tax line. What a $1,000,000 bid really costs, the cash needed on a $999,000 two-bedroom, and how buyers and sellers should offer and price.
Read →October 19, 2026
What Happens at an Upper East Side Co-op Board Interview? Questions, Timeline and How to Prepare in 2026
What a co-op board interview is, the questions boards ask, how long approval takes, what a board can and cannot legally do, and a worked number check on a $525,000 one-bedroom.
Read →October 20, 2026
Local Law 11 Façade Inspections and Special Assessments: What Upper East Side Co-op Buyers Should Check Before They Offer in 2026
What NYC's façade inspection law means for a co-op buyer: Safe, SWARMP and Unsafe reports, sidewalk shed rules, how a special assessment could hit your share, and what to ask before you offer.
Read →October 21, 2026
Can You Renovate an Upper East Side Co-op? Alteration Agreements, Board Approval, Costs and Timelines in 2026
What an alteration agreement is, what a board needs before you renovate, the fees and timeline before work starts, what renovation costs per square foot, and what to check before you offer.
Read →October 22, 2026
What Happens at a Co-op Closing in Manhattan? Documents, Cash Due, Timeline and a Closing-Day Checklist for 2026
The documents, cash due, timeline and closing-day checklist for a Manhattan co-op purchase, with a worked example on a $675,000 Yorkville one-bedroom.
Read →October 23, 2026
Buying a $1.375 Million Upper East Side Co-op: Is It a Jumbo Loan? Down Payment, Mansion Tax and Cash Needed in 2026
Whether a $1.375 million co-op loan is a jumbo, plus the down payment, $13,750 mansion tax, cash to close and monthly cost, with a worked example on a Yorkville two-bedroom.
Read →October 25, 2026
Buying a Newly Renovated Studio on the Upper East Side: What to Check on a $319,000 Yorkville Co-op in 2026
What a "newly renovated" studio co-op does and does not tell you, the documents to request, monthly cost, cash to close and sublet rules, with a worked example on a $319,000 Yorkville studio.
Read →October 28, 2026
Buying a Ground-Lease Co-op in Lenox Hill: Lease Expiration, Rent Resets, Financing and What to Ask Before You Offer in 2026
How a ground-lease co-op works, why the rent reset and lease expiration matter, a real Lenox Hill listing, and cash to close at $1.195 million, with the questions to ask before you offer.
Read →October 29, 2026
How to Make an Offer on an Upper East Side Apartment: Bidding, the Contract, the 10% Deposit and the New 45-Day Co-op Board Clock in 2026
What an offer includes, how negotiation and the contract work, the 10% deposit, contingencies and the new 45-day co-op board clock, with a worked example on a $549,000 Yorkville one-bedroom.
Read →